Written by Matkustelu.fi
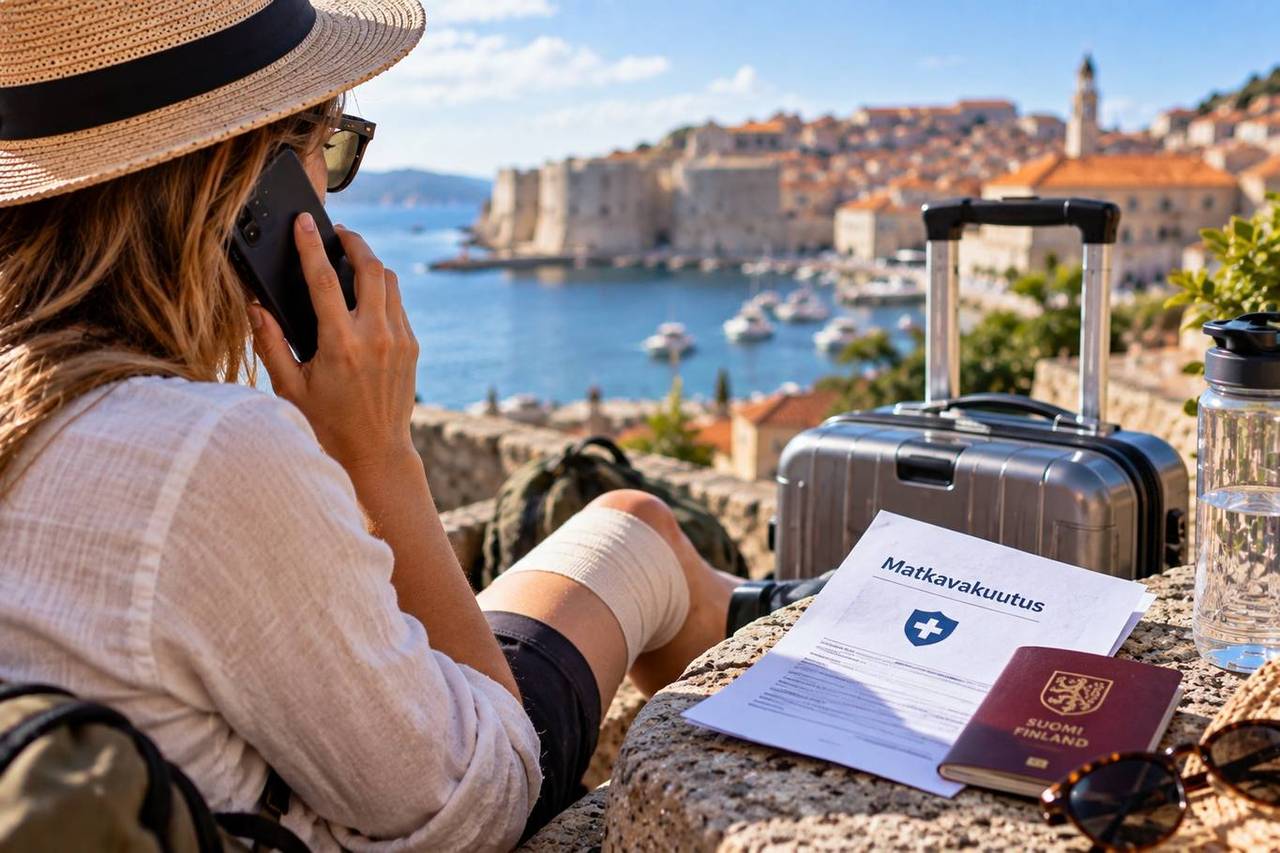
Travel insurance is the most important thing you pack. Compare policy types, coverage levels and deductibles — and see what yours must cover.
Travel insurance is one of the most important things a traveller should consider before departure. Although no one wants to think about illness, accidents, or lost luggage on vacation, these things unfortunately happen. Without proper insurance, unexpected situations can lead to bills of thousands of euros.
Why is travel insurance essential? First, healthcare abroad can be extremely expensive. For example, in the United States, a simple emergency room visit can cost thousands of dollars, and a hospital night can easily cost $10,000 or more. Outside of Europe, the European Health Insurance Card does not cover anything. A serious illness or accident without insurance can mean financial disaster.
Second, a trip cancellation or interruption can cause significant costs. Flights, hotels, and tours are often paid for in advance and are not refundable without insurance. If you have to return home for family reasons or get sick just before departure, travel insurance will cover the losses.
Third, lost or stolen luggage is unfortunately common. Thousands of bags are lost at airports every day, and travellers are often targets for thieves in tourist areas. Insurance covers lost items and helps you continue your journey.
What should travel insurance include? Basic coverage usually includes the following: medical expenses for travel illness and accidents (at least €100,000), trip cancellation and interruption, luggage damage, travel delay, and liability insurance. More comprehensive policies also include legal protection insurance and repatriation in case of illness.

Types of travel insurance
Insurance types can be divided into three main categories: Single-trip insurance is suitable for the occasional traveller and is valid for one trip. Annual or continuous travel insurance is worthwhile if you travel more than 2-3 times a year — it covers all trips during the year. Credit card insurance comes with many credit cards, but the coverage is often limited.
Comparison: Single-trip vs. annual insurance. A single-trip policy typically costs €20-80 depending on the duration and destination of the trip. A one-week trip to Europe costs about €20-30, while a three-week trip to Asia can cost €50-80. Annual insurance costs about €100-300 per year and includes an unlimited number of trips. If you travel 3+ times a year, annual insurance is usually more economical.
The pitfalls of credit card insurance: Many people think that the insurance that comes with their credit card is sufficient, but this is often not the case. Credit card insurance often has high deductibles (€100-200), the trip must be paid for with that card, coverage is often limited (e.g., only for trips of 30 days), and there may be a 48-hour activation period before the insurance takes effect.
Extreme sports and special situations: Basic insurance policies do not usually cover high-risk activities such as diving, mountaineering, motor sports, or skydiving. If you are planning such activities, you will need an extension or a special policy. The same applies to business trips — leisure travel insurance does not cover work-related travel.
How to choose the right policy
First, assess your travel habits: how often you travel, to which destinations, for how long, and what activities you engage in. Then, compare offers from different insurance companies. Pay attention to the coverage amounts (medical expenses at least €100,000), the size of the deductible, covered expenses, and exclusions.
Finnish travel insurance providers include If, LähiTapiola, Pohjola, Fennia, and Eurooppalainen. Online services like Vertaa.fi and Vakuutusmeklari help compare prices. Remember to read the insurance terms and conditions carefully — the cheapest is not always the best.
Practical tips for using your insurance: Always carry your insurance card and emergency number with you. Save the insurance certificate on your phone and in a cloud service. Report any damages to the insurance company immediately. Collect all receipts and documents for reimbursement. File a police report for stolen items.
Summary: Travel insurance is a small investment for peace of mind. A policy costing a few tens of euros can save you thousands of euros and a lot of stress. Don't go on a trip without it — it's the one piece of luggage you hope you'll never need, but you wouldn't want to be without.
Comparison table: policy types side by side
| Policy type | Price | Duration | Medical cover | Deductible | Best for |
|---|---|---|---|---|---|
| Single-trip | €20–80 per trip | 1 trip, 1–90 days | €100,000 – unlimited | €0–150 | 1–2 trips a year |
| Annual policy | €80–200 per year | Continuous, 45–90 days per trip | Usually unlimited | €0–100 | 3+ trips a year |
| Credit card cover | €0 (card fee) | 30–45 days | Often €500,000 cap | €100–300 | Short Europe trips, as a backup |
| SafetyWing / nomad cover | approx. $45 / 4 weeks | Unlimited, billed monthly | $250,000 | $250 | Trips over 3 months, remote work |
| Sports add-on | +€20–60 | On top of base policy | Per base policy | Per base policy | Diving, climbing, motorsport |
The real difference is not the price but the deductible and the medical cap. For the USA, Canada or Japan always pick unlimited medical cover, and on a long trip the maximum trip length matters more than the payout limits. Current prices and an insurer-by-insurer comparison are in the travel insurance comparison 2026.
Read next
See current policy prices and coverage levels in the travel insurance comparison 2026, check vaccines and your medicine kit in health while travelling, and make sure your documents are valid with the passport, ETIAS and visa guide. If you travel alone, read the complete solo travel guide.
Written by Matkustelu.fi
Published 10.3.2026
The Matkustelu.fi editorial team curates travel information and planning tips. Always verify changing rules, prices and timetables with the original sources.